Company Law / ROC Compliance
MGT-7 and MGT-7A for FY 2025-26: Due Date, Fees and How to File the Annual Return
Reviewed by CA Neeraj Rohilla, FCA — Chartered Accountant, Startup Advisory, Saket, New Delhi.
1. MGT-7 and MGT-7A due dates for FY 2025-26
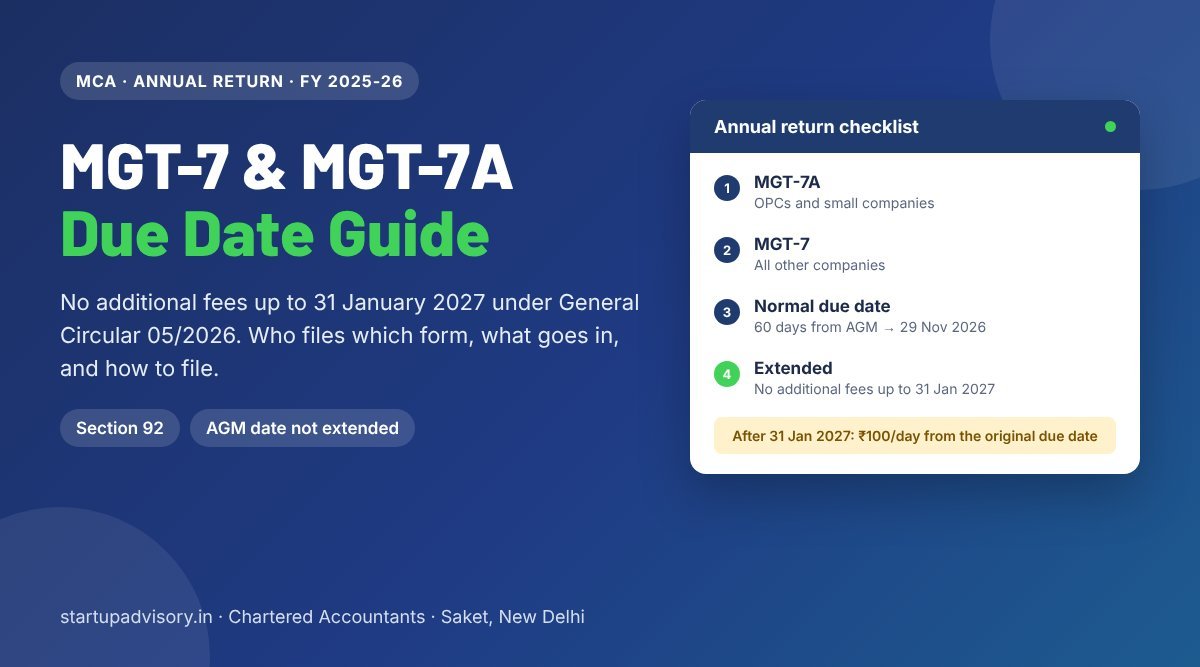
Section 92(4) of the Companies Act, 2013 requires every company to file its annual return with the Registrar within 60 days from the date of the AGM. Where no AGM is held, the 60 days run from the date on which the AGM should have been held, and the return goes with a statement of the reasons for not holding it.
| Your situation | Normal due date | Last date without additional fees (GC 05/2026) |
|---|---|---|
| AGM held on 30 September 2026 | 29 November 2026 | 31 January 2027 |
| AGM held earlier, say 15 September 2026 | 14 November 2026 | 31 January 2027 |
| AGM not held by 30 September 2026 | 29 November 2026 (60 days from when it should have been held) | 31 January 2027, but the AGM default stands |
| AGM held later under a Registrar’s extension | 60 days from that AGM | 31 January 2027, or the normal date if later |
| One Person Company (no AGM) | 29 November 2026 | 31 January 2027 |
The extended date is a fixed calendar date. It does not move with your AGM date, so a company with an early AGM gets the longest relief.
2. What General Circular 05/2026 says about the annual return
MCA issued General Circular No. 05/2026 on 24 October 2026 after representations from stakeholders for more time on FY 2025-26 annual filings. Paragraph 2(b) of the circular allows companies to file:
Two other paragraphs matter just as much:
- The AGM is not extended (paragraph 3). The circular is not to be read as extending the statutory time for holding AGMs, and companies that missed those timelines stay liable under the Act.
- Late fees run from the original date (paragraph 4). A filing made after the circular lapses pays all fees, including additional fees, “from the date when such filings were actually due under the Act”.
The same circular extends AOC-4 and its variants to 31 December 2026. We cover that side in AOC-4 and MGT-7 due dates extended for FY 2025-26.
3. MGT-7 or MGT-7A: which form does your company file?
| Form | Who files it | What is different |
|---|---|---|
| MGT-7A (abridged annual return) | One Person Companies and small companies | Shorter form with fewer disclosures. Signed by the company secretary, or by a director where there is no company secretary. |
| MGT-7 (annual return) | Every other company: private companies that are not small companies, public companies, Section 8 companies, and holding or subsidiary companies excluded from the small-company definition | Full disclosures on members, directors, meetings, remuneration and penalties. Signed by a director and the company secretary, or a practising company secretary where there is no company secretary. |
Small-company status is tested on paid-up capital and turnover, and the limits were raised recently, so many companies that filed MGT-7 last year now file MGT-7A. Check your FY 2025-26 figures against the current limits (see our note on the small company definition for FY 2025-26). A holding or subsidiary company and a Section 8 company cannot be a small company.
4. What the annual return contains
Section 92(1) lists what the annual return must state as at the close of the financial year. For FY 2025-26 that is 31 March 2026:
- Registered office, principal business activities and particulars of holding, subsidiary and associate companies
- Shares, debentures and other securities, and the shareholding pattern
- Members and debenture holders, with changes since the previous year
- Promoters, directors and key managerial personnel, with changes during the year
- Meetings of members, the Board and its committees, with attendance
- Remuneration of directors and key managerial personnel
- Penalties or punishments imposed on the company, its directors or officers, and details of compounding of offences
- Matters relating to certification of compliance and other disclosures as prescribed
Section 92(3) also requires a company with a website to place its annual return there, and the Board’s report must give the web link.
5. Signing and MGT-8 certification
- MGT-7 is signed by a director and the company secretary. Where the company has no company secretary, a practising company secretary signs in place of the company secretary.
- MGT-7A of an OPC or small company is signed by the company secretary, or by a director where there is no company secretary.
- Form MGT-8: the annual return of a listed company, or of a company with paid-up capital of ₹10 crore or more or turnover of ₹50 crore or more, must be certified by a practising company secretary in Form MGT-8 and attached to MGT-7.
Every signatory needs a valid Class 3 DSC registered on MCA V3, and each director needs an active DIR-3 KYC status. Expired DSCs and deactivated DINs are the most common last-week blockers.
6. Filing fees and additional fees
The normal filing fee for MGT-7 and MGT-7A depends on the company’s nominal share capital under the Companies (Registration Offices and Fees) Rules, 2014, from ₹200 for capital below ₹1 lakh to ₹600 for capital of ₹1 crore or more. A company without share capital pays ₹200.
A late annual return pays an additional fee of ₹100 per day, with no upper limit. Under General Circular 05/2026:
| Filed on (AGM held 30 September 2026) | Additional fee |
|---|---|
| On or before 29 November 2026 | Nil |
| 30 November 2026 to 31 January 2027 | Nil (relaxed by GC 05/2026) |
| 15 February 2027 | About ₹7,800 (78 days from 30 November 2026) |
| 31 March 2027 | About ₹12,200 (122 days from 30 November 2026) |
Missing 31 January 2027 by a day therefore costs about ₹6,400 (64 days), because the fee is counted back to the original due date.
7. Penalties for not filing the annual return
- Section 92(5): a penalty of ₹10,000 on the company and on every officer in default, plus ₹100 for each day the failure continues, up to ₹2 lakh for the company and ₹50,000 for an officer. This is on top of the additional fee.
- Section 164(2): a director of a company that has not filed financial statements or annual returns for any three continuous financial years is disqualified from being reappointed, or appointed in any other company, for five years.
- Section 248: long-running non-filing is one of the grounds on which the Registrar can begin striking off a company.
8. How to file MGT-7 or MGT-7A on MCA V3
- Pick the right form. Test small-company status on the FY 2025-26 figures. OPCs and small companies use MGT-7A, everyone else MGT-7.
- Collect the data. Shareholding as at 31 March 2026 and transfers during the year, directors and KMP with appointment and cessation dates, the dates of Board, committee and general meetings with attendance, and director and KMP remuneration.
- File AOC-4 first. The annual return reports turnover and net worth, which should match the financial statements already on the MCA record. AOC-4 is due without additional fees by 31 December 2026.
- Fill the web form on MCA V3. Log in with the user ID linked to a director or the company secretary, open MGT-7 or MGT-7A, and let the form pre-fill master data. Correct any mismatch in the master data with the relevant event form first.
- Attach and certify. Attach the list of shareholders and debenture holders, any clarification letter, and MGT-8 where required. Affix the DSCs of the signatories.
- Pay and save the SRN. Pay the normal fee before 31 January 2027 and keep the challan with the statutory registers.
9. Documents checklist
- Signed financial statements for FY 2025-26 and the AOC-4 SRN
- AGM notice, minutes and the date of the AGM (or reasons for not holding it)
- Register of members, share transfers and allotments during the year (PAS-3, SH-4 records)
- Register of directors and KMP, with DIR-12 filings for any change
- List of Board, committee and general meetings with attendance
- Director and KMP remuneration figures
- Details of any penalty, compounding or show-cause notice
- Valid DSCs and DIN KYC status of the signatories; MGT-8 from a practising CS if the thresholds apply
10. Other FY 2025-26 deadlines to keep in view
| Date | Filing | Source |
|---|---|---|
| 31 October 2026 | MSME-1 for April to September 2026 | Companies Act |
| 21 November 2026 | Income tax return of a company (AY 2026-27) | CBDT press release, 28 September 2026 |
| 31 December 2026 | AOC-4, AOC-4 (XBRL), AOC-4 (CFS), AOC-4 NBFC (Ind AS), AOC-4 CFS NBFC (Ind AS) without additional fees | MCA GC 05/2026 |
| 31 December 2026 | CRA-4 (cost audit report in XBRL) without additional fees | MCA GC 06/2026, 27 October 2026 |
| 31 January 2027 | MGT-7 and MGT-7A without additional fees | MCA GC 05/2026 |
ADT-1, DIR-12 and the LLP forms are not covered by either circular and keep their normal dates. For the full year see our ROC annual compliance calendar.
- MCA General Circular No. 05/2026 dated 24 October 2026 (File No. Policy-17/111/2022-CL-V-MCA), “Relaxation of additional fees and extension of time for filing of Financial Statements and Annual Returns under the Companies Act, 2013”, paragraphs 2 to 4
- MCA General Circular No. 06/2026 dated 27 October 2026 (F.No. Policy-17/52/2020-CL-V), relaxation of additional fees for filing CRA-4 for FY 2025-26 up to 31 December 2026
- Companies Act, 2013: Sections 92, 96, 134, 164, 248 and 403
- Companies (Management and Administration) Rules, 2014: Rule 11 (Forms MGT-7, MGT-7A and MGT-8)
- Companies (Registration Offices and Fees) Rules, 2014 (normal and additional fees)
Circulars are published on mca.gov.in.
This article is general information, not legal advice. Confirm your company’s position with a qualified professional before acting.
How Startup Advisory Can Help
Startup Advisory is a CA-led firm in Saket, New Delhi. We file annual returns for private limited companies, OPCs and Section 8 companies across Delhi NCR:
- A check of whether your company files MGT-7 or MGT-7A this year, and whether MGT-8 applies.
- MGT-7 or MGT-7A prepared from your registers and filed well before 31 January 2027, with practising CS signature where needed.
- AOC-4 filed first, by 31 December 2026, so the two filings match.
- Clean-up of pending DIR-12, PAS-3 or ADT-1 filings that would block the annual return.
Call 9311972982 or book a free consultation.