Startup Advisory provides audit and assurance services from Saket, New Delhi — the audits the law requires (statutory audit under the Companies Act, 2013, tax audit under Section 44AB / Section 63 of the Income-tax Act, 2025, internal audit under Section 138), the audits lenders ask for (stock and concurrent audit), the audits owners commission to protect the business (store, fixed asset, investigation), and the due diligence that deals depend on.
 Required by law: statutory audit, tax audit, internal audit (above Rule 13 limits).Asked for by banks: stock audit, concurrent audit.Assets and inventory: fixed assets audit, asset verification & tagging, store audit.When something is wrong: investigation & forensic audit.Deals and lenders: financial due diligence, secretarial due diligence.Provider: Startup Advisory, CA firm in Saket, New Delhi 110030. Call 9311972982.
Reviewed by CA Neeraj Rohilla, FCA — Chartered Accountant, Startup Advisory, Saket, New Delhi.
Most businesses arrive with a request from someone else — the Registrar, the income-tax department, a bank, a buyer. This table maps who needs each audit, the law or document behind it, and what you receive at the end.
| Service | Who needs it | Basis | What you get |
|---|---|---|---|
| Statutory audit | Every company; LLPs above ₹40 lakh turnover or ₹25 lakh contribution | Companies Act, 2013; LLP Act, 2008 | Audit report (with CARO 2020 where applicable) |
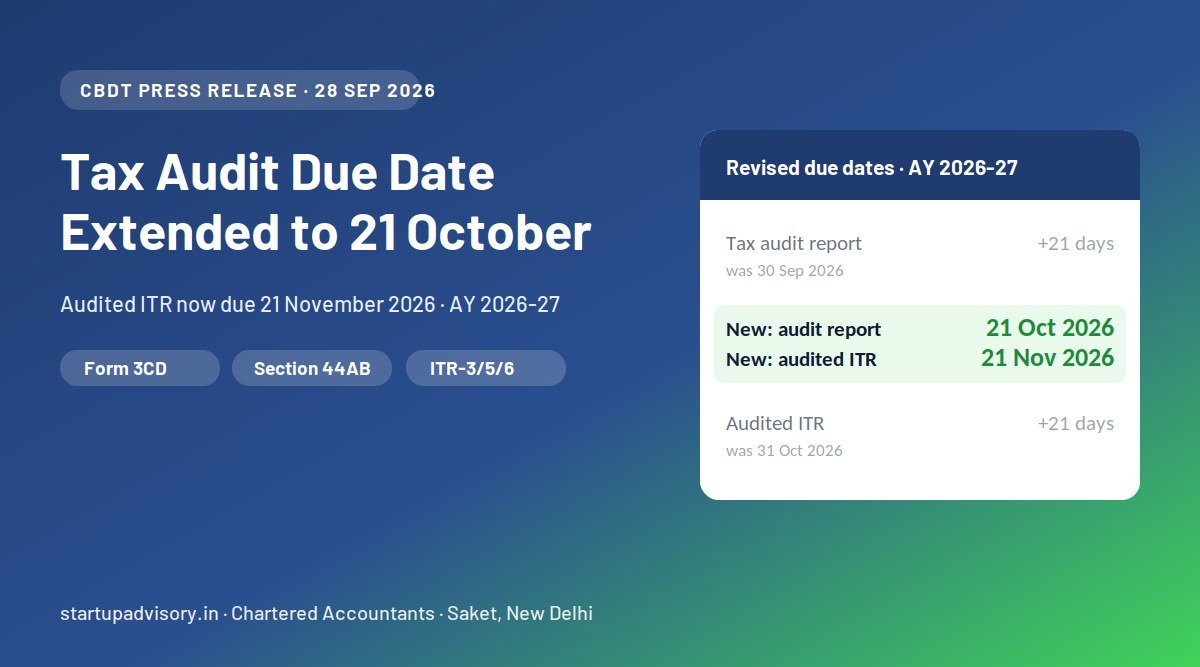
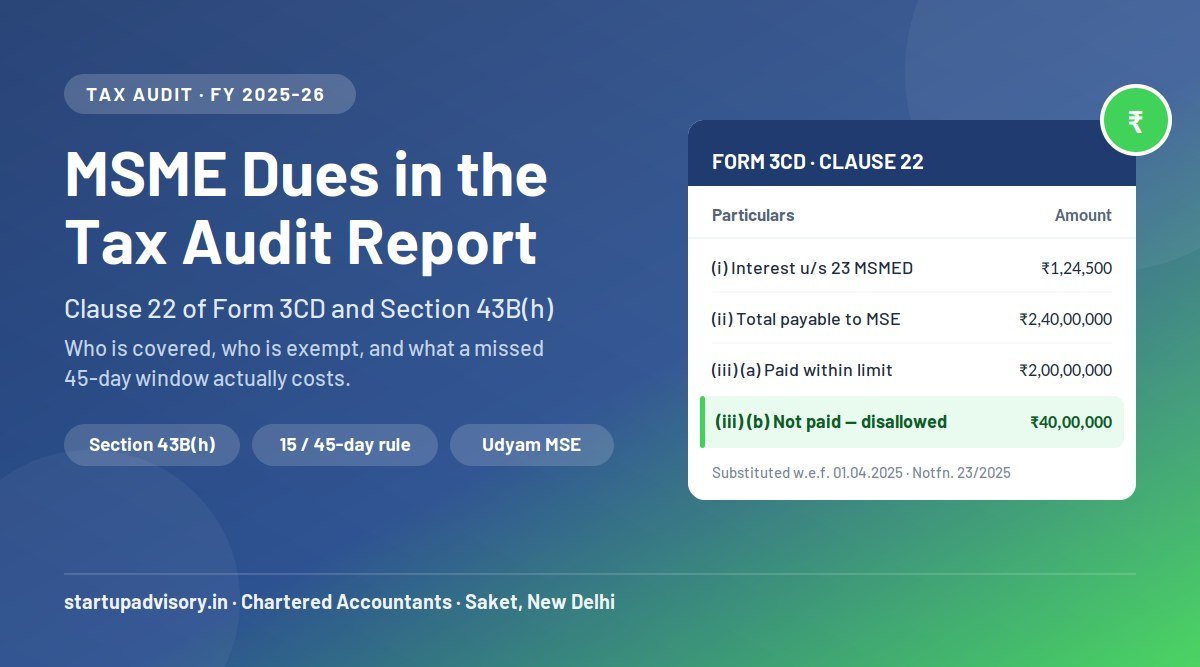
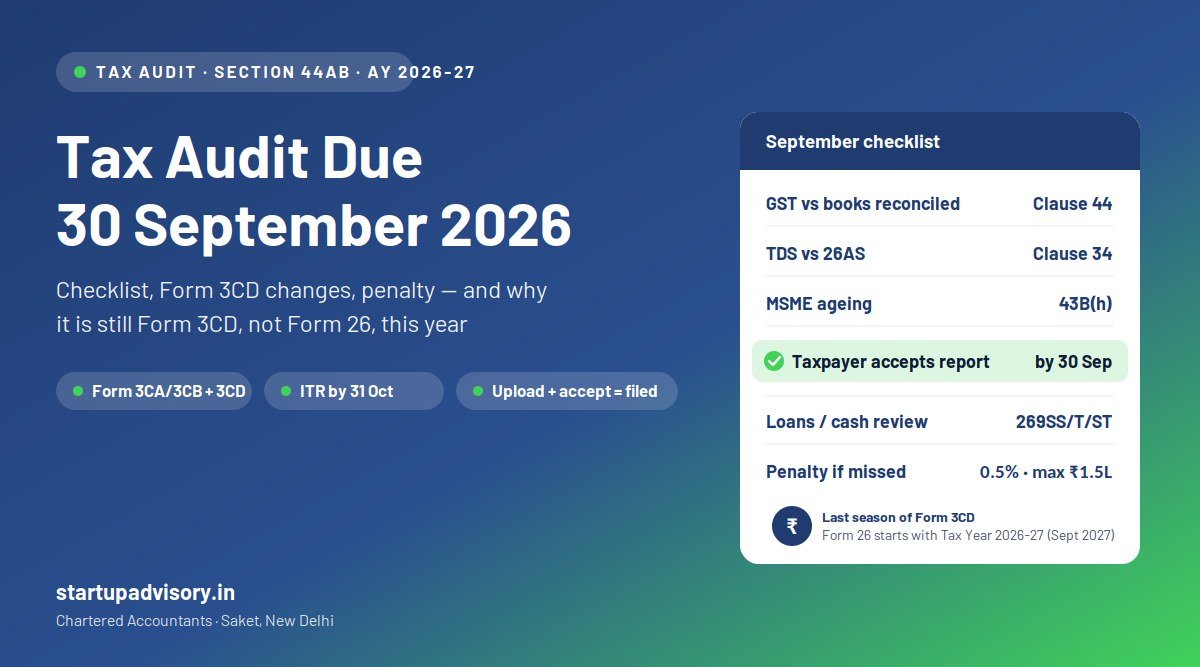
| Tax audit | Business turnover > ₹1 crore (₹10 crore with ≤5% cash); professionals > ₹50 lakh; certain presumptive cases | Section 44AB (1961 Act); Section 63 (2025 Act) from Tax Year 2026-27 | Form 3CA/3CB + 3CD; Form 26 from Tax Year 2026-27 |
| Internal audit | Listed companies and companies above Rule 13 limits; voluntary for others | Section 138, Companies Act; Rule 13 | Quarterly reports to board / audit committee |
| Concurrent audit | Banks (RBI guidelines, 18 Sept 2019); businesses by choice | RBI circular; management policy | Monthly transaction audit reports |
| Stock audit | Working capital borrowers, as required by the lender | Sanction terms / bank credit policy | Bank-format report, drawing power |
| Store audit | Management | Voluntary | Control findings, leakage, savings |
| Fixed assets audit | Management; supports CARO 3(i) | Voluntary | Reconciled FAR, adjustment entries |
| Asset verification & tagging | Management; supports CARO 3(i)(b) | Voluntary | Tagged assets, exception reports |
| Investigation audit | Board, promoters, counsel, lenders | Voluntary; ICAI FAIS | Factual report with evidence file |
| Financial due diligence | Buyers, sellers, lenders, JV partners | Transaction-driven | FDD report, SPA inputs |
| Secretarial due diligence | Buyers, lenders, investors, IPO candidates | Transaction-driven | Secretarial DD report, remediation plan |
CA-led: every engagement is planned and signed off by a chartered accountant; reports carry a UDIN where ICAI requires one.Fixed fee, scoped first: we agree scope, timeline and fee in writing before fieldwork starts.Independence first: Section 144 of the Companies Act bars a company’s auditor from also keeping its books or acting as its internal auditor. We check conflicts before we accept any audit, and act on only one side of a transaction.Findings you can act on: every report ranks findings by impact and pairs each one with a practical fix, an owner and a date.One desk for the follow-through: where independence allows, the same team can fix what the audit finds — through bookkeeping, Virtual CFO, GST and income-tax support.
Vishal Singh
Ajay Philip

Pranshu Gaur

Ravish Mehta

Mohit Aggarwal

Sanjeev Sharma

Realtoadvisors

Sakshi Gupta
Rudranath Trip
Yash Rohilla
Sandro Cottus

Azan Hosein Photography
Neetu Yadav
Fresh guides on tax, GST and startup compliance from our CA team.
Share your details — our experts call you back. We use these details only to respond to you. See our Privacy Policy.