Tax & ITR
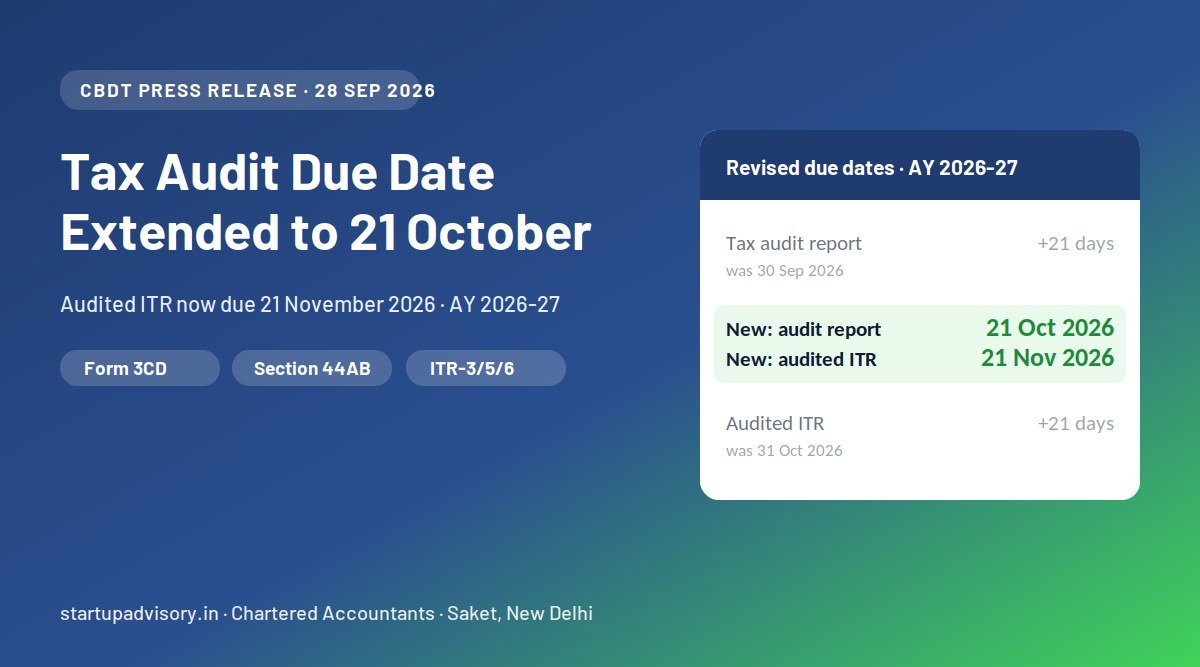
Tax Audit Due Date Extended to 21 October 2026; Audited ITR Now Due 21 November 2026
Reviewed by CA Neeraj Rohilla, FCA — Chartered Accountant, Startup Advisory, Saket, New Delhi.
What CBDT announced
The Central Board of Direct Taxes issued a press release from New Delhi on 28 September 2026, titled “CBDT extends due date for furnishing Return of Income for AY 2026-27 in respect of persons subject to audit under the Income-tax Act, 1961”. The operative text reads:
Note the order of the logic. CBDT extended the return due date, and the audit-report date moved with it. The audit report is due one month before the return due date, so pushing the return to 21 November puts the report on 21 October.
Revised due dates for AY 2026-27
| Compliance | Earlier date | Date now |
|---|---|---|
| Tax audit report (Form 3CA/3CB with Form 3CD) and other audit reports, for persons at S. No. 2 of the Table below Explanation 2 to Section 139(1) | 30 September 2026 | 21 October 2026 |
| Income-tax return of those persons (ITR-3 / ITR-5 / ITR-6 as applicable) | 31 October 2026 | 21 November 2026 |
| Transfer-pricing cases: Form 3CEB and tax audit report | 31 October 2026 | 31 October 2026 (not mentioned in the release) |
| Transfer-pricing cases: return of income | 30 November 2026 | 30 November 2026 (not mentioned in the release) |
| Belated / revised return, AY 2026-27 | 31 December 2026 | 31 December 2026 (not mentioned in the release) |
| Non-audit business / presumptive ITR | 31 August 2026 | Already past (see our belated return guide) |
Who is covered
The release describes the covered class by reference to the statute: persons at S. No. 2 in the Table below Explanation 2 to Section 139(1), whose return was due on 31 October 2026. In practice that is the ordinary audit case: companies, and businesses and professionals whose accounts must be audited under Section 44AB or any other law. The precise list, including where partners of audited firms and trusts sit, should be read from the formal order when it is issued.
The release extends the “specified date” for the report of audit under the provisions of the Act, not only Form 3CD. For the covered persons, other audit reports tied to the same specified date should move to 21 October as well. That includes Forms 10B and 10BB for charitable trusts and institutions in the same category. Treat this as our reading of the release, and confirm it against the order.
What the extension does not change
- Transfer-pricing cases. The release is silent on assessees who file Form 3CEB. Unless the order adds them, their audit report stays on 31 October 2026 and their return on 30 November 2026. That leaves a TP taxpayer with an audit date after 21 October but still before 21 November. Do not assume the 21 November date applies to you.
- The 31 December cut-off. The belated and revised return date is untouched. An audit case that files on 21 November has about six weeks to revise. In a normal year that window is two months.
- Interest. Interest under Sections 234B and 234C is calculated to the date of filing or payment, not the due date, so filing later costs 1% a month on unpaid tax either way. On Section 234A, some past extension orders from CBDT specifically kept interest running where self-assessment tax was above ₹1 lakh. This press release says nothing either way. Pay self-assessment tax by 31 October 2026 and file the return when it is ready.
- The acceptance step. A tax audit report is filed only when the CA uploads it and the taxpayer accepts it from their own e-filing login. The extension moves that deadline to 21 October; it does not remove the step.
- Penalty. Section 271B still applies: 0.5% of turnover or gross receipts, capped at ₹1,50,000, unless there is reasonable cause. It now runs from 22 October instead of 1 October.
How the extension came about
Professional associations across the country had asked CBDT to move the audit date to 31 October 2026. They pointed to the compressed calendar after the 31 August non-audit deadline, the overlap with GST and MCA work, and the changes to reporting requirements this year. The Rajasthan Tax Consultants Association also filed a writ petition in the Rajasthan High Court asking for the same relief. That case was heard on 25 and 28 September 2026. CBDT announced its decision the same evening, giving 21 days rather than the month that had been sought.
This is the second year in a row that the audit date has moved late. For AY 2025-26, CBDT moved the specified date from 30 September to 31 October 2025, also announced in the last week of September.
What we recommend
- If your audit report is ready, file it. The extra time is review time, not a reason to hold a finished report. The portal will be busiest again in the week before 21 October.
- If your CA has uploaded the report, accept it now. A report left pending for acceptance is the most common reason audits miss the date.
- Use the 21 days for the clauses that attract questions. These are MSME dues under Section 43B(h) (Clause 22; see our Clause 22 guide), the TDS default reconciliation, GST turnover against the books, and cash transactions under Sections 269SS, 269T and 269ST.
- Pay self-assessment tax by 31 October 2026 until the formal order confirms how Section 234A interest is treated.
- If you file Form 3CEB, plan to 31 October unless the order says otherwise.
- Keep the formal order on file. Once it is issued, keep the order number with the audit papers. It is the document that supports the date if a penalty notice is ever raised.
For the full pre-audit checklist, the Form 3CD changes in force this year and the applicability tests, see our tax audit deadline guide and who needs a tax audit.
- CBDT Press Release dated 28 September 2026, “CBDT extends due date for furnishing Return of Income for AY 2026-27 in respect of persons subject to audit under the Income-tax Act, 1961”, issued by the Commissioner of Income Tax (Media & Technical Policy) and Official Spokesperson, CBDT, and published on the Income Tax Department’s official X handle @IncomeTaxIndia
- Section 139(1), Explanation 2 and the Table below it; Section 44AB; Sections 234A, 234B, 234C and 271B, Income-tax Act, 1961
- CBDT Press Release dated 25 September 2025 (PIB): specified date for audit reports for AY 2025-26 extended from 30 September 2025 to 31 October 2025
The formal CBDT order/notification had not been issued when this article was published. We will add its number here once it is.
This article is general information, not tax advice. It is based on CBDT’s press release of 28 September 2026; the formal order may define the covered class or add conditions. Confirm your own due date with a qualified professional before relying on it.
How Startup Advisory Can Help
Startup Advisory is a CA-led firm in Saket, New Delhi. For proprietors, firms, LLPs and companies across Delhi NCR, we use the extra weeks where they count:
- Section 44AB audit, Form 3CA/3CB-3CD, DSC upload with UDIN, and the taxpayer acceptance chased well before 21 October.
- Self-assessment tax computed and paid by 31 October so the interest question does not arise.
- Audited ITR filed by 21 November, with loss carry-forward preserved and time left to revise before 31 December.
- Transfer-pricing and trust clients kept on their own dates until the formal order says otherwise.
Call 9311972982 or book a free consultation.