Income Tax / TDS
Form 16A Is Now Form 131: The New TDS Certificate Under the Income-tax Rules, 2026
Reviewed by CA Neeraj Rohilla, FCA — Chartered Accountant, Startup Advisory, Saket, New Delhi.
1. What Form 131 is
Form 131 is the certificate a deductor gives you when it has deducted tax at source from a payment that is not salary. Its full title in the Rules is a “Certificate under section 395(4) for tax deducted at source other than on salary paid to an employee under section 392 or pension or interest income of specified senior citizen under section 393(1)”. The Income Tax Department’s own FAQ is headed “Form No. 131 (Earlier Form No. 16A)”.
You get one when a client deducts TDS from your professional fees, a company deducts TDS from your contract bill, a tenant deducts TDS from rent, or a bank deducts TDS from interest. It proves the tax was deducted and deposited against your PAN, so you can claim the credit in your return.
| Before 1 April 2026 | From 1 April 2026 | |
|---|---|---|
| Certificate | Form 16A | Form 131 |
| Section | Section 203, Income-tax Act, 1961 | Section 395(4), Income-tax Act, 2025 |
| Rule | Rule 31, Income-tax Rules, 1962 | Rule 215(1) [Table: Sl. No. 2], Income-tax Rules, 2026 |
| Generated from | Quarterly statement 26Q / 27Q | Quarterly statement Form 140 / Form 144 |
| Frequency | Quarterly | Quarterly |
| Where it comes from | TRACES | TRACES |
2. Old vs new: the forms that changed
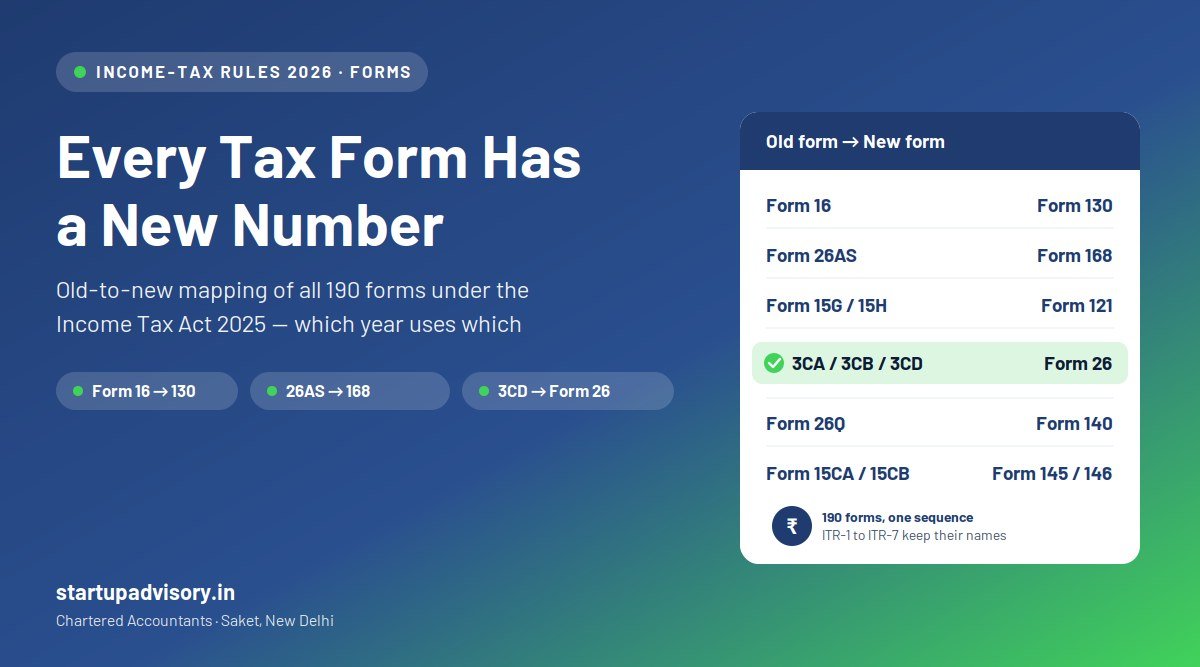
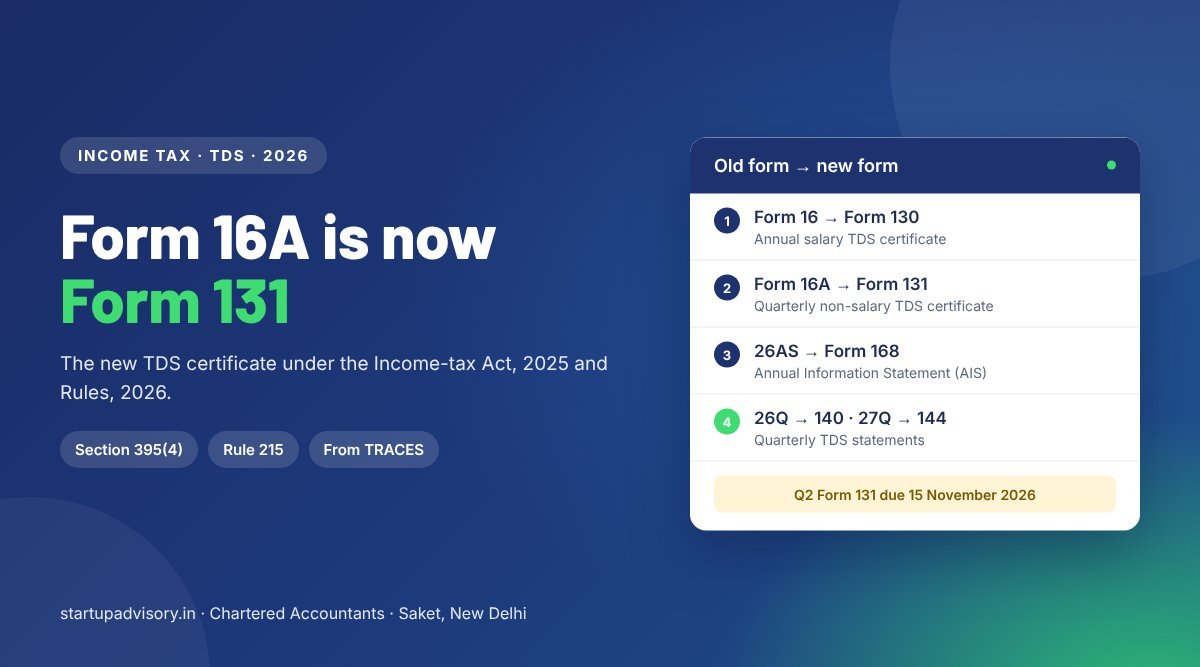
These are the TDS forms a business or taxpayer handles most often. Every row below is taken from the Income Tax Department’s FAQs on Forms 130, 131 and 168. For the full list of 190 forms, see our complete old-to-new form mapping.
| Old form (1961 Act) | New form (2025 Act) | What it is | Who gives it |
|---|---|---|---|
| Form 16 | Form 130 | Annual TDS certificate on salary, pension or interest of a specified senior citizen | Employer or specified bank |
| Form 16A | Form 131 | Quarterly TDS certificate on other payments | Any deductor |
| Form 26AS | Form 168 | Annual Information Statement (AIS) for your PAN | Viewed on the e-filing portal |
| 24Q | Form 138 | Quarterly TDS statement for salary | Employer (filed with the department) |
| 26Q | Form 140 | Quarterly TDS statement for other payments to residents | Deductor (filed with the department) |
| 27Q | Form 144 | Quarterly TDS statement for payments to non-residents | Deductor (filed with the department) |
The ITR forms (ITR-1 to ITR-7) keep their names. The renumbering applies to the certificates, statements and applications in the Appendix to the Income-tax Rules, 2026.
3. Form 16A or Form 131: which one applies
The year of the deduction decides it, not the date you issue the certificate.
- Tax deducted up to 31 March 2026 (FY 2025-26 and earlier) falls under the Income-tax Act, 1961. Those certificates are Form 16A, including the January to March 2026 certificates issued in June 2026.
- Tax deducted from 1 April 2026 (Tax Year 2026-27 onward) falls under the Income-tax Act, 2025. Those certificates are Form 131. The first ones were due on 15 August 2026 for April to June 2026.
So in the ITR you file in 2026 for FY 2025-26 you match Form 16A and 26AS. In the return for Tax Year 2026-27, filed in 2027, you will match Form 131 and Form 168.
4. Due dates for Form 131
The FAQ sets the rule: Form 131 is issued within 15 days from the due date of furnishing the quarterly statement. For Tax Year 2026-27 that works out as follows.
| Quarter of deduction | Issue Form 131 by |
|---|---|
| April to June 2026 (Q1) | 15 August 2026 |
| July to September 2026 (Q2) | 15 November 2026 |
| October to December 2026 (Q3) | 15 February 2027 |
| January to March 2027 (Q4) | 15 June 2027 |
Form 130 (salary) is different: it is issued once a year, by 15 June after the end of the tax year.
5. How a deductor issues Form 131
- File the quarterly statement. Report the deduction in Form 140 (residents) or Form 144 (non-residents) with the deductee’s correct PAN, and the challan or Form 137 book-entry details.
- Wait for processing. TRACES generates Form 131 only after the statement is processed.
- Download from TRACES. Request and download the certificates for the quarter from the TRACES portal. The department’s FAQ says a certificate prepared any other way is “not a legal or valid TDS certificate”.
- Sign it. The person responsible for deduction signs it, digitally or by hand.
- Send it within 15 days of the statement due date, one certificate per deductee per quarter.
- Correct if needed. If the PAN, amount or section is wrong, file a revised statement in Form 140/144, then download and re-issue Form 131. A lost certificate can be re-issued marked as a duplicate.
Software that still prints “Form 16A” for a Tax Year 2026-27 deduction is out of date. Check your accounting and TDS software before the 15 November run. For contractor payments, see our guide to TDS on contractors under section 393.
6. Checklist when you receive Form 131
- Title: it should say Form No. 131 for deductions from 1 April 2026, and come from TRACES.
- Your PAN and name are correct. A wrong PAN means the credit goes to someone else.
- Deductor’s TAN and name match the party that paid you.
- Quarter and period are right, and you have one certificate for each quarter in which tax was deducted.
- Amount paid and TDS match your invoices and the amount actually short-paid to you.
- Section shown matches the nature of the payment (contract, fees, rent, interest and so on).
- Signature is present, digital or manual.
- Cross-check in Form 168 (AIS) on the e-filing portal. If the certificate shows TDS but the AIS does not, ask the deductor to correct its statement.
- Keep it on file. You do not attach it to your return, but you need it if the credit is questioned.
7. Form 130 (was Form 16) in brief
The FAQ on Form 130 is headed “Form No. 130 (Earlier Form No. 16)” and states that Form 130 replaces Form 16. It is the certificate under section 395(4)(b) for TDS on salary under section 392, or on pension or interest of a specified senior citizen under section 393(1). It comes from rule 215(1) [Table: Sl. No. 1].
- Issued annually by the employer, or by the specified bank for a specified senior citizen, by 15 June after the tax year.
- Generated from the quarterly salary statement in Form 138 and downloaded from TRACES.
- Part A has the employer and employee details, Part B the summary of tax deducted, and Part C the salary computation (Annexure-I) or the senior citizen details (Annexure-II).
- If you change jobs, each employer issues Part A and Part B for its period.
Your first Form 130 will cover salary for Tax Year 2026-27, so it arrives by 15 June 2027.
8. Form 168 (was 26AS) in brief
The FAQ on Form 168 is headed “Form No. 168 (Earlier Form No. 26 AS)”. Form 168 is the Annual Information Statement (AIS) under section 510 of the 2025 Act and rule 245 of the 2026 Rules. It shows the TDS, TCS, tax payments, refunds and the financial transactions that banks, employers, mutual funds and others report against your PAN.
- Open it on the e-filing portal at incometax.gov.in: log in and choose View Annual Information Statement (AIS).
- The Taxpayer Information Summary (TIS) is a category-wise summary of the AIS.
- If an entry is wrong, duplicated or not yours, use Give Feedback in the AIS.
- Report all your income in the return, even if something is missing from the AIS.
9. Common mistakes
- Issuing a self-made certificate from accounting software instead of the TRACES download. It is not a valid TDS certificate.
- Labelling a Tax Year 2026-27 certificate as Form 16A, or quoting old 1961-Act sections such as 194C or 194J in a Tax Year 2026-27 statement.
- Filing the quarterly statement late or with a wrong PAN, so the certificate cannot be generated or shows the wrong deductee.
- Deductees filing their return without checking Form 168, then getting a mismatch notice for TDS that was never reported.
- Forgetting that each deductor gives a separate certificate for each quarter. One missing quarter means missing credit.
- Income Tax Department, Form No. 131 (Earlier Form No. 16A): FAQs
- Income Tax Department, Form No. 131 [See rule 215(1) (Table: Sl. No. 2)]
- Income Tax Department, Form No. 130 (Earlier Form No. 16): FAQs
- Income Tax Department, Form No. 168 (Earlier Form No. 26 AS): FAQs
- Income-tax Act, 2025 (sections 392, 393, 395 and 510) and Income-tax Rules, 2026 (rules 215 and 245), as referenced in the FAQs above, read on 14 November 2026
This article is general information, not tax advice. It reflects the Income Tax Department’s FAQs on Forms 130, 131 and 168 as read on 14 November 2026. Check the latest position on the e-filing portal or TRACES before you act.
How Startup Advisory Can Help
Startup Advisory is a CA-led firm in Saket, New Delhi that handles TDS end to end for businesses across Delhi NCR:
- Quarterly statements: Forms 138, 140 and 144 prepared, filed and corrected.
- Certificates: Form 130 and Form 131 downloaded from TRACES, signed and sent on time.
- Reconciliation: your books matched to Form 168 (AIS) before you file, using our TDS calculator and ITR advisory.
Call 9311972982 or book a free consultation.