Company Law / ROC Compliance
MCA Extends AOC-4 and MGT-7 Due Dates for FY 2025-26: AOC-4 to 31 December 2026, MGT-7 to 31 January 2027 (General Circular 05/2026)
Reviewed by CA Neeraj Rohilla, FCA — Chartered Accountant, Startup Advisory, Saket, New Delhi.
1. What MCA announced on 24 October 2026
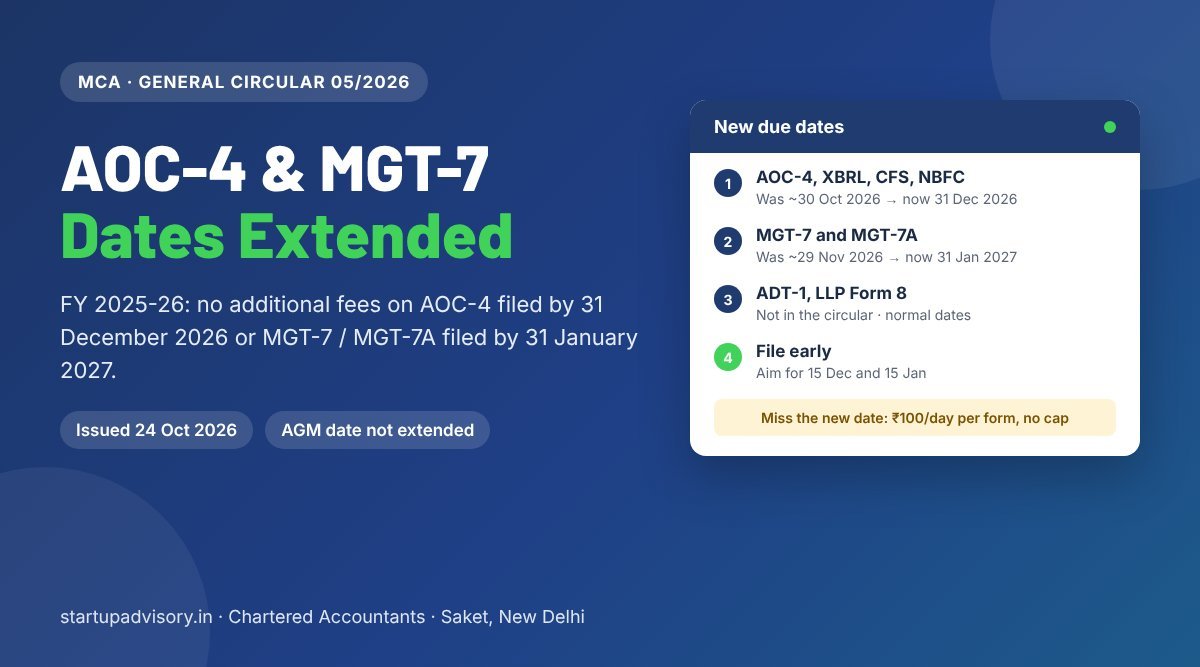
On 24 October 2026 the MCA announced on its official handle, @MCA21India, that it had issued General Circular No. 05/2026 of the same date:
The announcement lists two filing deadlines:
- Financial statements: Form AOC-4, AOC-4 (XBRL), AOC-4 (CFS), AOC-4 CFS NBFC (Ind AS) and AOC-4 NBFC (Ind AS), by 31 December 2026.
- Annual returns: Form MGT-7 and Form MGT-7A, by 31 January 2027.
Filing within these dates attracts only the normal filing fee. No additional (late) fee is charged for the delay up to the new date.
2. Old and new due dates for FY 2025-26
Normally Section 137 of the Companies Act, 2013 requires the financial statements to be filed within 30 days of the AGM, and Section 92 requires the annual return within 60 days of the AGM. For most companies the AGM for FY 2025-26 was held on or before 30 September 2026.
| Form | What it is | Normal due date (AGM on 30 Sep 2026) | Extended date without additional fees |
|---|---|---|---|
| AOC-4 | Financial statements and Board’s report | 30 October 2026 | 31 December 2026 |
| AOC-4 (XBRL) | Financial statements in XBRL, for companies required to file in XBRL | 30 October 2026 | 31 December 2026 |
| AOC-4 (CFS) | Consolidated financial statements | 30 October 2026 | 31 December 2026 |
| AOC-4 NBFC (Ind AS) and AOC-4 CFS NBFC (Ind AS) | Standalone and consolidated statements of NBFCs under Ind AS | 30 October 2026 | 31 December 2026 |
| MGT-7 | Annual return | 29 November 2026 | 31 January 2027 |
| MGT-7A | Abridged annual return for OPCs and small companies | 29 November 2026 | 31 January 2027 |
If your AGM was earlier than 30 September, your normal dates were earlier too, so the relief is longer. The extended dates are fixed calendar dates and do not depend on when the AGM was held.
3. Which companies benefit
- Private and public companies that held their FY 2025-26 AGM and have not yet filed AOC-4 or MGT-7.
- One Person Companies. An OPC holds no AGM and normally files AOC-4 within 180 days of the year-end, which was 27 September 2026. As the relaxation is given form-wise for FY 2025-26, an OPC that has not yet filed can file AOC-4 by 31 December 2026 and MGT-7A by 31 January 2027 without additional fees.
- Small companies filing MGT-7A, now that the higher small-company limits have brought many more companies into that category (see our note on CARO and cash flow statements for small companies).
- Groups and NBFCs filing consolidated or Ind AS versions of AOC-4.
- Companies whose AGM was extended by the Registrar. Their normal due dates fell later, but they too can file without additional fees up to the extended dates.
The relief helps most where a company is still waiting on its audit, its XBRL tagging, or a director’s DSC, or where the MCA V3 forms raised validation errors close to the deadline.
4. What the extension does not change
The MCA announcement names only the AOC-4 forms and MGT-7/MGT-7A. Treat these as unchanged unless MCA says otherwise:
- ADT-1 (auditor appointment): within 15 days of the AGM, so about 15 October 2026 for a 30 September AGM.
- DIR-12, MGT-14, PAS-3 and other event-based forms: their own 30-day timelines.
- MSME-1 for April to September 2026: due 31 October 2026.
- LLP Form 8 (statement of account and solvency): due 30 October 2026. LLP Form 11 was due 30 May 2026. LLPs are governed by the LLP Act, 2008, and this circular is issued under the Companies Act.
- Income tax return: a company’s return for AY 2026-27 is due 21 November 2026 under the CBDT’s separate extension (see our post on the CBDT extension).
5. What happens if you file after the extended date
Late filing of AOC-4 and MGT-7 attracts an additional fee of ₹100 per day, per form, under the Companies (Registration Offices and Fees) Rules, 2014, with no upper limit. Continued default also exposes the company and its officers to penalties under Sections 137 and 92, and directors to disqualification under Section 164(2) after three years of non-filing.
In earlier relaxations of this kind MCA said that a filing made after the extended date pays additional fees counted from the original due date, not from the extended one. Plan on the same rule here. If you miss 31 December 2026, an AOC-4 for a 30 September AGM would carry additional fees from 31 October 2026, not from 1 January 2027.
| Filed on | AOC-4 additional fee (AGM 30 Sep 2026) | MGT-7 additional fee (AGM 30 Sep 2026) |
|---|---|---|
| On or before the extended date | Nil | Nil |
| After the extended date (if fees run from the original date) | ₹100 a day from 31 October 2026, so over ₹6,000 by early January | ₹100 a day from 30 November 2026, so over ₹6,000 by early February |
6. Why MCA extended the dates
On 9 October 2026 the Institute of Company Secretaries of India wrote to the MCA asking for the due dates of all annual filing forms to be extended to 31 December 2026 without additional fees, pointing among other things to the CBDT’s extension of tax audit and ITR dates. Until 24 October no extension had been issued, and AOC-4 for most companies was due within the week.
The circular gives more than ICSI asked for on the annual return, which now runs to 31 January 2027, but it covers only the AOC-4 and MGT-7 forms rather than every annual form.
7. How to use the extra time
- Check that the AGM was held. Confirm the AGM date, the minutes and the resolutions adopting the accounts. The extension assumes a valid AGM.
- File ADT-1 if it is pending. It is not covered, so its additional fees have been running since 15 days after the AGM.
- Finish AOC-4 by mid-December. Attach the signed financial statements, auditor’s report and Board’s report. For XBRL companies, leave time for tagging and validation. Make sure the signing directors’ DSCs are valid and their DIR-3 KYC status is active.
- Prepare MGT-7 or MGT-7A in parallel. Shareholding as at 31 March 2026, the list of directors and KMP, meetings held, and the certification by a practising company secretary where MGT-7 requires it.
- File early in the window. The MCA V3 portal slows down sharply in the last fortnight before an extended date. Aim for 15 December for AOC-4 and 15 January for MGT-7.
- Keep the challans. Save the SRN and payment confirmation for each form in the company’s statutory records.
8. Other deadlines that still apply
| Date | Filing | Law |
|---|---|---|
| 30 October 2026 | LLP Form 8 (FY 2025-26) | LLP Act, 2008 |
| 31 October 2026 | MSME-1 for April to September 2026 | Companies Act |
| 21 November 2026 | Income tax return of a company (AY 2026-27) | Income-tax Act |
| 31 December 2026 | AOC-4 and its variants (FY 2025-26), extended | Companies Act, GC 05/2026 |
| 31 January 2027 | MGT-7 and MGT-7A (FY 2025-26), extended | Companies Act, GC 05/2026 |
For the full year, see our ROC annual compliance calendar for FY 2025-26, which we have updated for this circular.
9. Mistakes to avoid
- Assuming the AGM date moved too. It did not. Only filing time is extended.
- Letting ADT-1 slide with AOC-4. ADT-1 is not in the circular.
- Applying the dates to LLPs. LLP Form 8 is still due 30 October 2026.
- Waiting until the last week. Portal congestion, DSC expiry and validation errors cause most late fees in an extension year.
- Filing MGT-7 before the AGM details are final. The annual return reports the AGM and shareholding, so get the minutes signed first.
- MCA General Circular No. 05/2026 dated 24 October 2026, “Relaxation of additional fees and extension of time for filing of Financial Statements and Annual Returns for the Financial Year 2025-26 under the Companies Act, 2013”, as announced on the Ministry of Corporate Affairs’ official X handle @MCA21India on 24 October 2026. Read the full circular on mca.gov.in before relying on any condition not stated in the announcement.
- Companies Act, 2013: Sections 92, 96, 99, 137, 139, 164 and 403
- Companies (Registration Offices and Fees) Rules, 2014 (additional fees for delayed filing)
- CBDT Press Release dated 28 September 2026 (ITR for audit cases, AY 2026-27, due 21 November 2026)
This article is general information, not legal advice. It is based on MCA’s official announcement of General Circular 05/2026. Confirm your company’s position against the full circular and with a qualified professional before acting.
How Startup Advisory Can Help
Startup Advisory is a CA-led firm in Saket, New Delhi. We handle ROC annual filings for private limited companies, OPCs and Section 8 companies across Delhi NCR:
- A quick check of where your FY 2025-26 filings stand, including any pending ADT-1 or DIR-12.
- AOC-4, AOC-4 (XBRL) and AOC-4 (CFS) prepared and filed well before 31 December 2026.
- MGT-7 or MGT-7A filed before 31 January 2027, with PCS certification where needed.
- Statutory audit and board and AGM documentation if your accounts are still open.
Call 9311972982 or book a free consultation.